Does Paying Off Loans Raise Credit Score
So, you're wondering if paying off loans will give your credit score a major boost? Well, let me tell you, it's not exactly a free ticket to a perfect credit score, but it's d...
So, you're wondering if paying off loans will give your credit score a major boost? Well, let me tell you, it's not exactly a free ticket to a perfect credit score, but it's definitely a step in the right direction. Think of it like getting a gold star on your credit report - it's a good thing, but there's more to the story.
Paying off loans is like deleting a bad selfie from your social media profile - it gets rid of the ugly stuff, but it doesn't automatically make you look like a supermodel. Your credit score is made up of many factors, including payment history, credit utilization, and credit age, so paying off loans is just one piece of the puzzle. But, it's a big piece, so don't underestimate its power!
The Credit Score Factor
Your credit score is like a report card for your financial habits, and paying off loans is like getting an A+ in responsibility. It shows lenders that you can handle debt and pay it back on time, which is a major key to unlocking better credit. However, if you've got other credit skeletons in your closet, like missed payments or high credit utilization, paying off loans won't magically erase those issues.
Must Read
But, here's the thing: paying off loans can have a ripple effect on your credit score. For example, when you pay off a loan, you're reducing your debt-to-income ratio, which can make you look more attractive to lenders. And, if you're paying off high-interest loans, you're saving money on interest, which can free up more cash flow for other important things, like saving or investing.
 Does Paying off Collections Improve Your Credit Score? - Self. Credit
Now, I know what you're thinking: "How long will it take for my credit score to improve after paying off loans?" Well, it's not like a microwave dinner - you can't just pop it in and expect instant results. It can take several months to a few years for your credit score to fully recover, depending on your individual circumstances.
The Surprising Facts
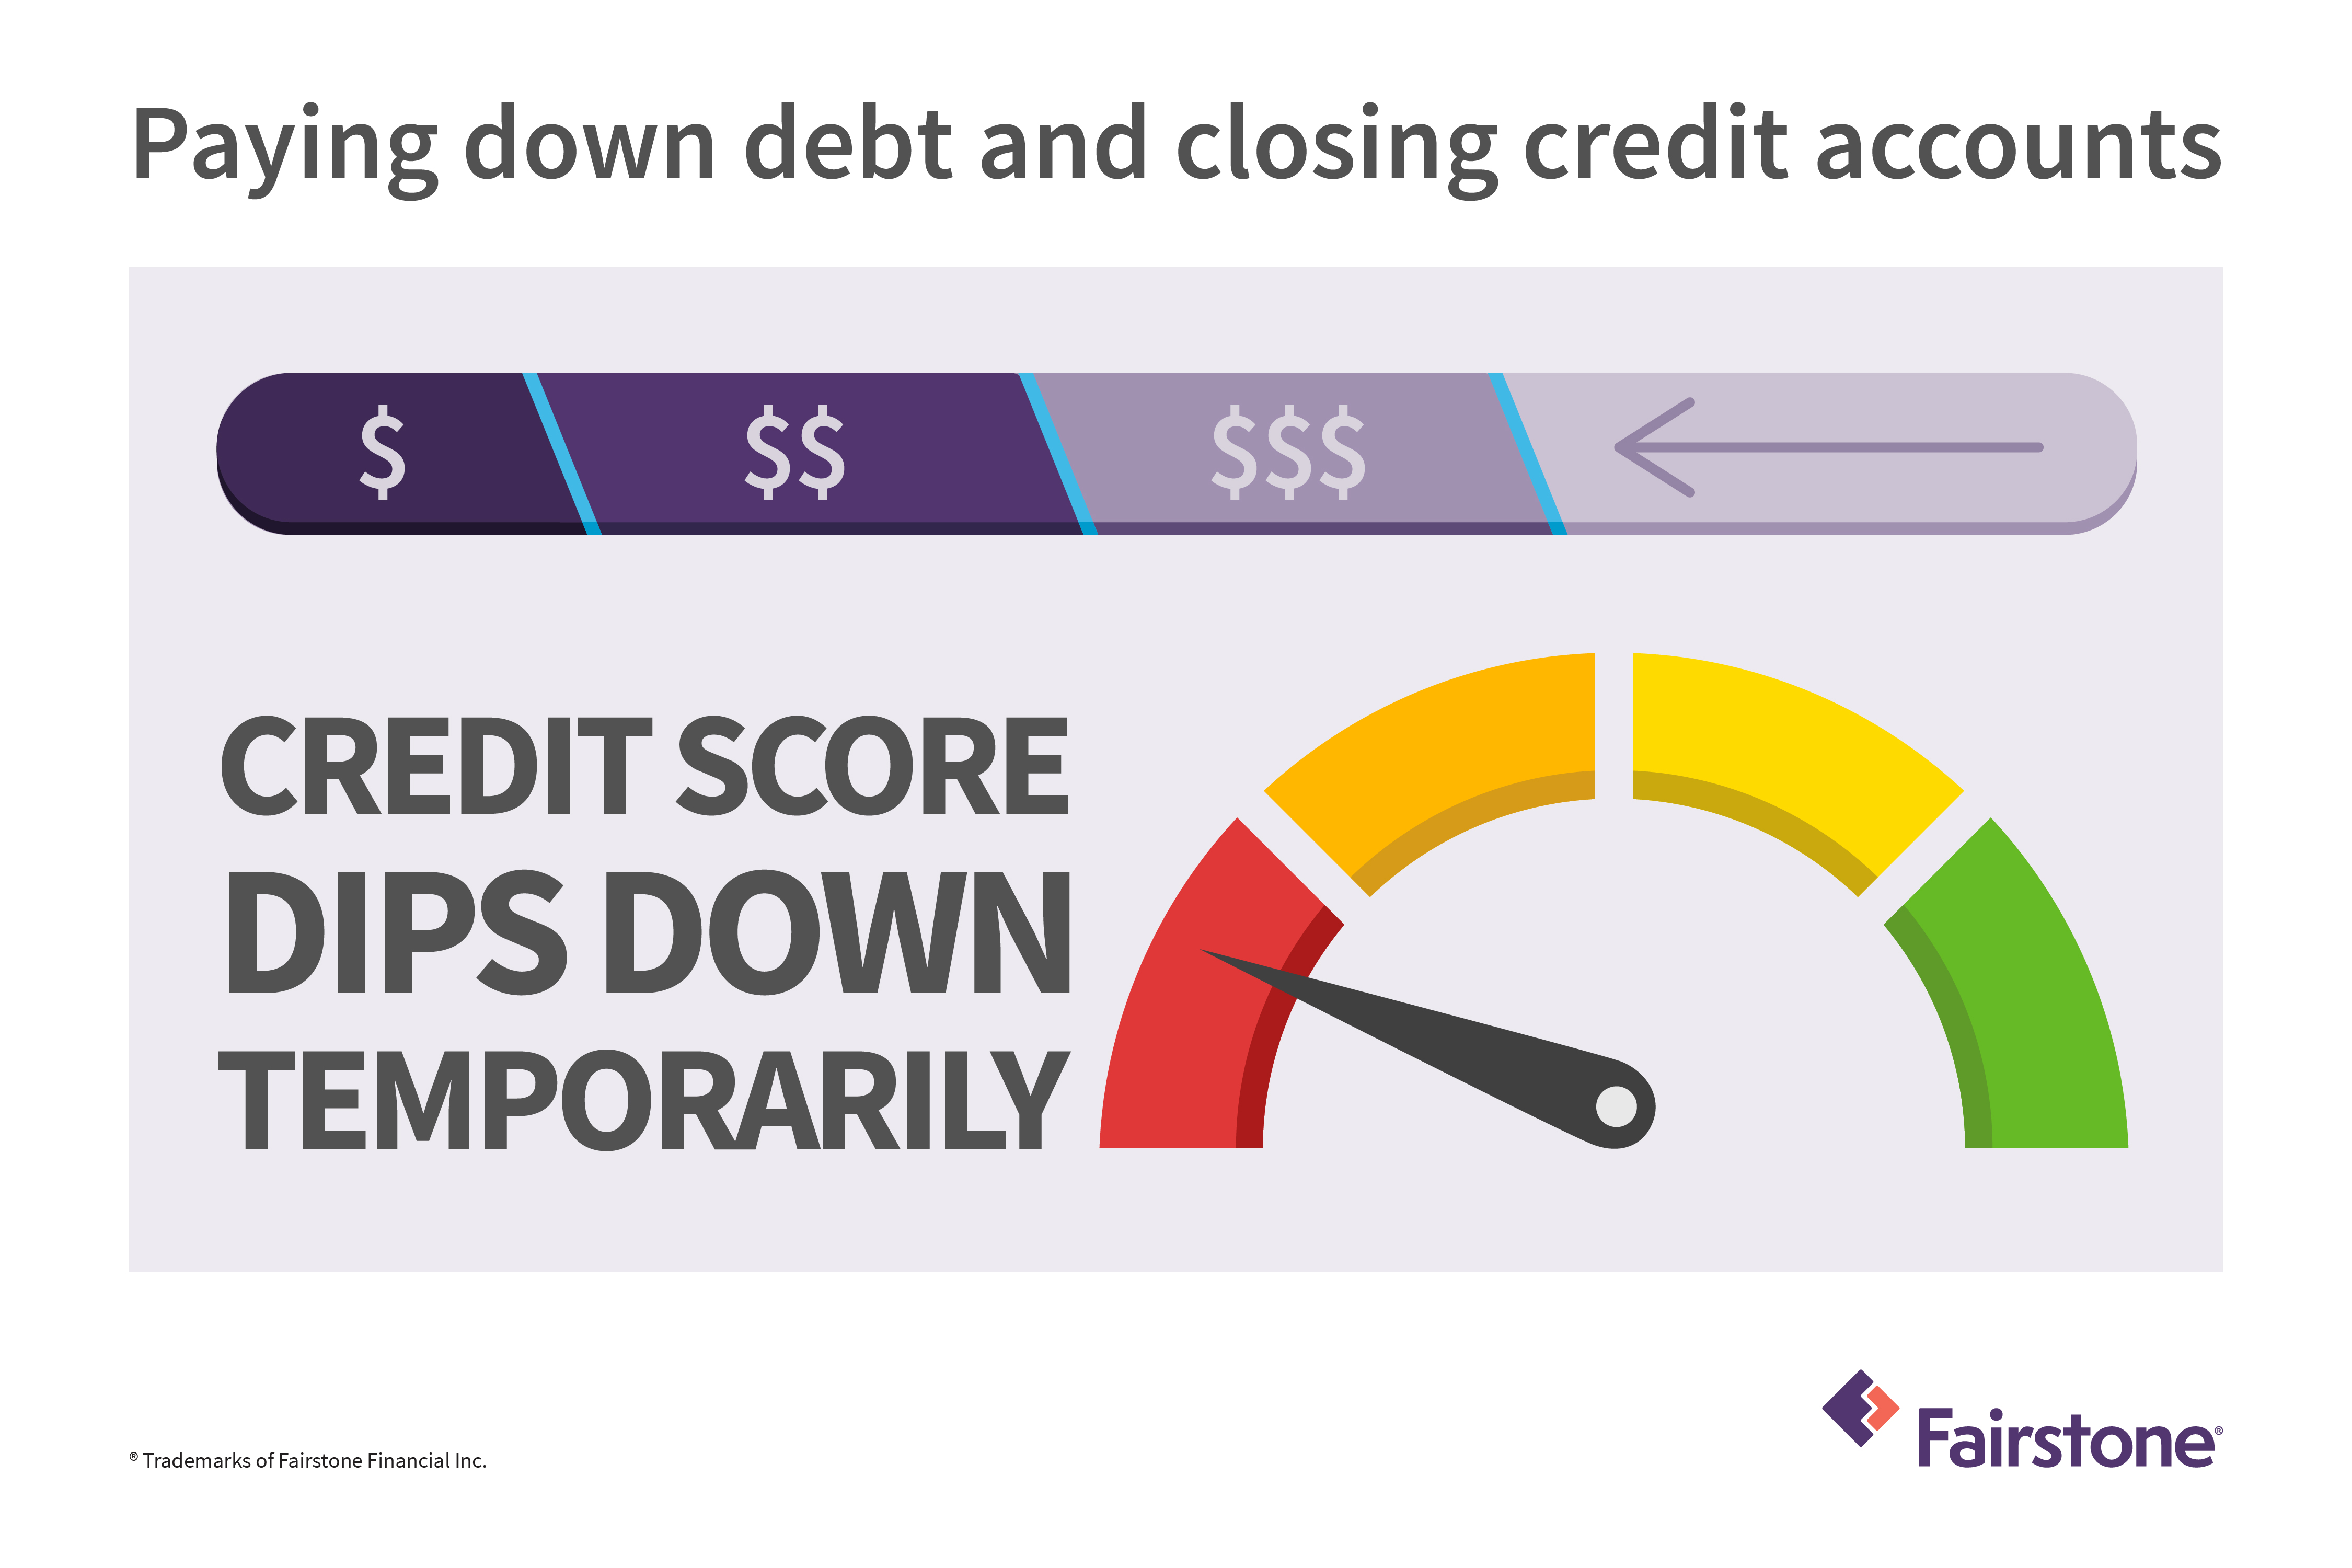
Here's a fun fact: did you know that paying off loans can actually lower your credit score in the short term? It's called the credit utilization conundrum - when you pay off a loan, you're reducing your overall credit utilization, but you're also reducing the number of accounts you have in good standing. It's like a credit Catch-22, but don't worry, it's temporary!
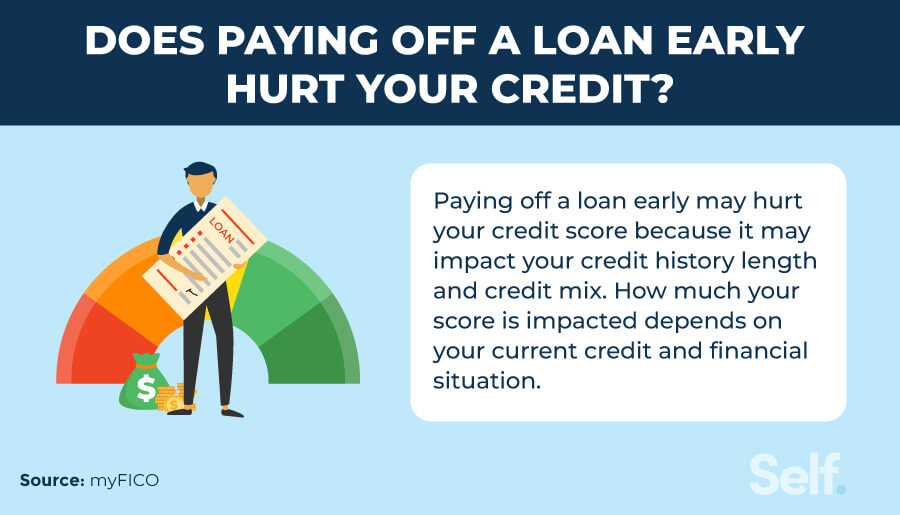 Does Paying Off a Loan Early Hurt Your Credit? Here's What to Know
And, here's another juicy tidbit: paying off loans can also impact your credit age. If you pay off a old loan, you're essentially erasing a long credit history, which can actually hurt your credit score. It's like getting rid of a vintage car - it may be old, but it's still a valuable asset!
In conclusion, paying off loans is a great step towards improving your credit score, but it's not a magic bullet. It's like losing weight - it takes time, effort, and a solid plan to see real results. So, keep paying off those loans, and stay patient - your credit score will thank you in the long run!
